Formal Recourse
Administrative litigation governs the legal reconciliation of discrepancies between textile importers and border authorities regarding the classification, valuation, or origin of foreign goods. Customs dispute resolution functions as the primary mechanism for correcting errors in duty assessment when an entry summary clashes with internal audit records. Manufacturers sourcing raw silk or synthetic fibres from overseas markets utilize this process to recover overpaid levies resulting from miscoded harmonized system chapters.
Border agents evaluate documentation such as commercial invoices, packing lists, and certificates of origin to determine whether an entry qualifies for preferential tariff treatment under existing trade agreements. When the importer produces evidence that contradicts the initial assessment, the agency adjusts the final liability and releases any held shipment.
Regulatory Mechanism
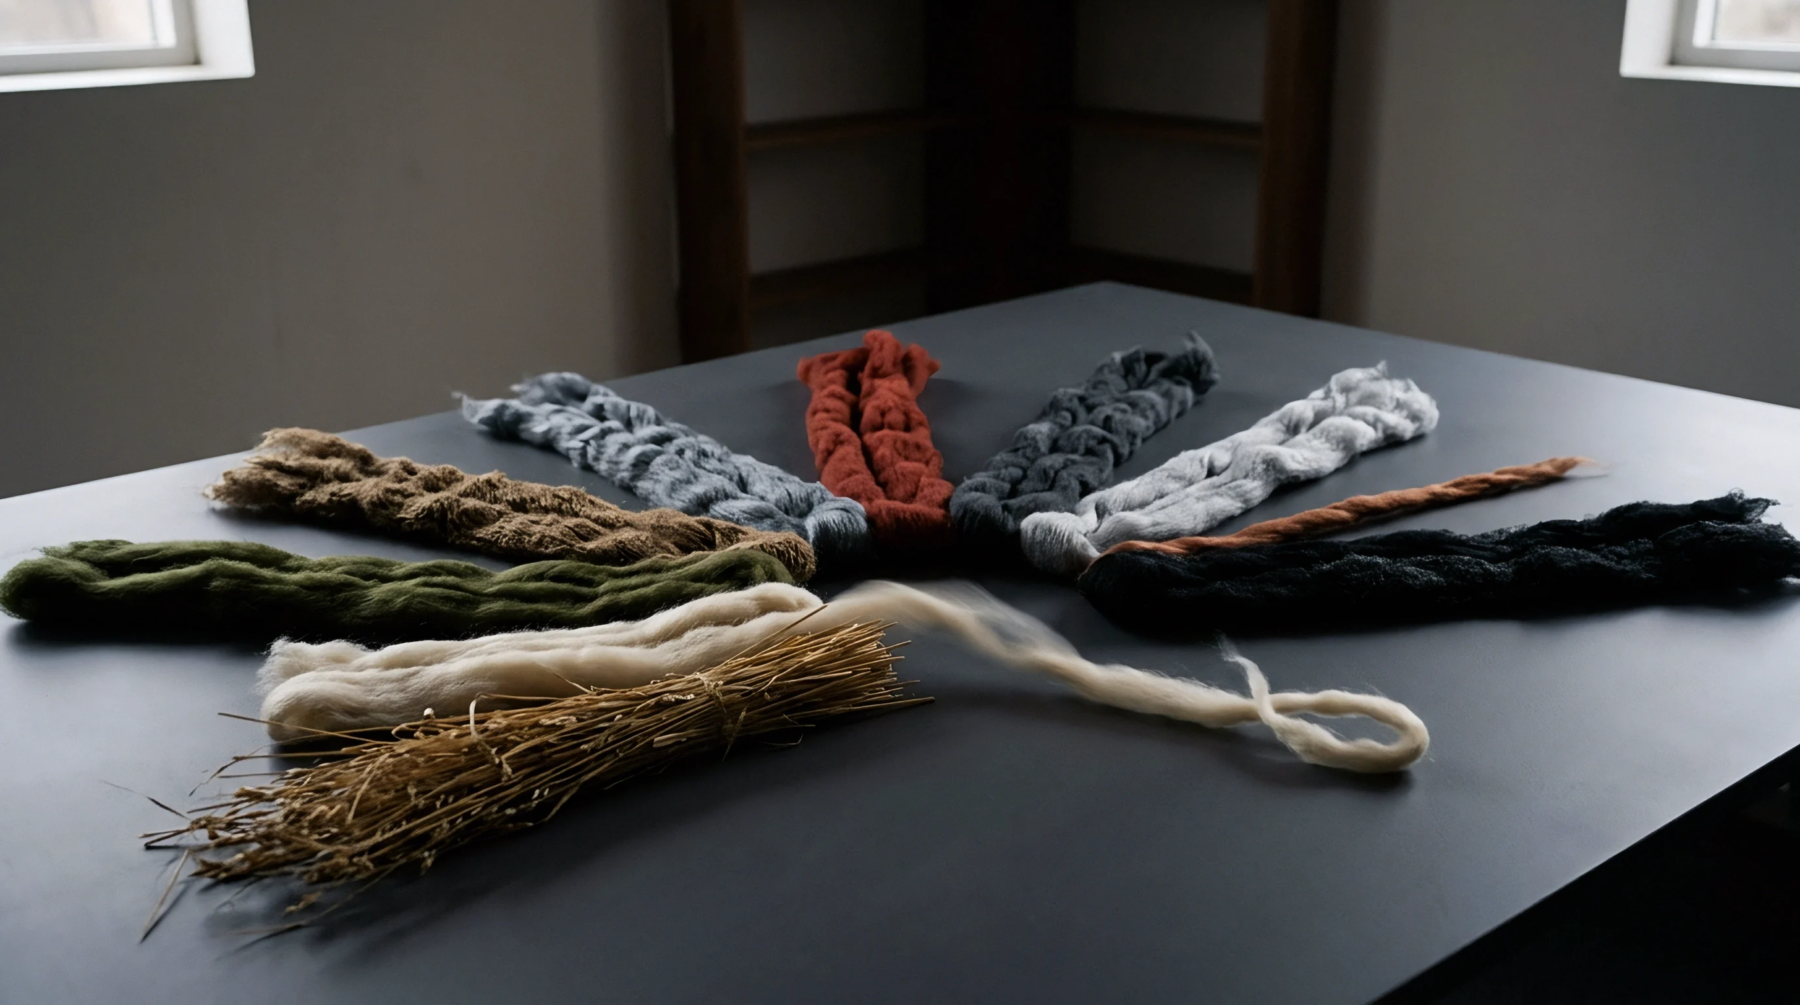
Formal petitions require a detailed brief containing the specific tariff line items and the factual grounds for the disagreement. Officers review the submission against established commodity codes that define the physical construction of a textile sample. A lab technician identifies the material composition or thread count of a fabric to confirm if the classification is correct.
If the results prove that the item belongs in a duty-free category rather than a taxed group, the agency voids the assessment. The importer submits these corrections through a portal that logs every request. Each petition moves through a hierarchical review where local officers verify the technical claims before escalating the matter to regional specialists.
Success depends on the ability to demonstrate that the textile sample matches the physical standards required for the requested code.
Economic Consequence
Financial exposure fluctuates based on the accuracy of these administrative challenges. Companies that maintain clean records avoid the long delays associated with formal audits of their global supply chain. Excessive reliance on inaccurate declarations prompts a scrutiny cycle that targets every box of finished apparel entering the country.
Unresolved differences increase the final landed cost per unit, which alters the margin available for retail sales. Efficient management of these disagreements reduces overhead by reclaiming capital previously locked in unnecessary deposits. Importers recover funds only after the regulatory body confirms the validity of the technical data.
A stable system ensures that taxes accurately reflect the physical reality of the goods rather than an administrative oversight.
Jurisdictional Boundary
Sovereign law defines the limit where these petitions stop exerting legal force. National statutes outline the timeframe for filing, which typically starts from the moment of liquidation. Appeals move outside the standard administrative loop if the agency maintains a refusal after the final internal review.
Courts assume authority over the claim once the statutory limit for administrative action passes. Judges apply the letter of the law to the provided evidence to determine if the government acted within its prescribed powers. Arbitration offers an alternative for private parties to fix values for internal accounting without changing the official tax record.
Final liability rests upon the conclusion of this legal process.